United Rentals Shares Trade Below Market Valuation Despite Strong Third-Quarter Earnings
Analyst Mike Khouw argues the heavy equipment lessor offers a discounted entry point as infrastructure demand supports revenue growth.
By Beatriz Soto ·
United Rentals (NYSE: URI) shares are currently trading at a valuation lower than the broader market average, according to Mike Khouw, an analyst at Tidal. Khouw noted that the company’s forward Price-to-Earnings ratio stands at approximately 17.3 times, based on forward estimates of $61.10 per share. On an Enterprise Value-to-EBITDA basis, the stock trades at about 8.8 times the projected $9.25 billion in EBITDA for the fiscal year ending in 2027.
Khouw pointed out that United Rentals is growing revenues, earnings, and EBITDA at a faster rate than the capitalization-weighted S&P 500. He described this dynamic as an opportunity to purchase superior growth at a discounted multiple. The company’s recent third-quarter earnings report supported this view, with results exceeding expectations and the company raising its forward outlook. Sell-side analysts have responded by revising their estimates upward, a trend Khouw identified as a reliable short-term investment factor.
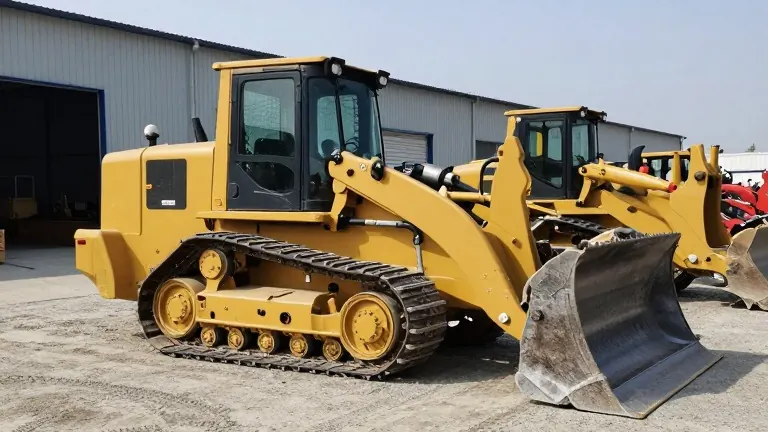
The backdrop for United Rentals’ performance includes a recovery in nonresidential construction. This sector has driven improving and resilient rental rates for the equipment lessor. While Khouw acknowledged that a potential slowdown in data center construction could become a future headwind, he stated that broader infrastructure demand remains strong. The company provides heavy equipment, such as compact track loaders and bulldozers, to clients working on these projects.
Khouw advised that while the stock appears cheap relative to the wider market, it is not undervalued relative to its own history. The share price currently sits roughly 20% to 25% above its five-year average multiple. He suggested that the historical multiple may have been too low for a business with United Rentals’ scale and capital efficiency. However, he noted that mean reversion back to those historical levels remains a downside risk for investors.
To address this valuation tension, Khouw recommended selling cash-covered puts as an entry strategy. This approach allows investors to collect a premium while acknowledging both the company’s growth and the risk of its elevated historical multiple. With United Rentals’ implied volatility hovering between 42% and 45%, the options market offers a sufficient premium for this trade.
If the stock price continues to rise, the put options expire worthless, and the seller keeps the premium. Khouw described this yield as a high-probability return that can outperform fixed income. If the stock price declines toward the five-year average multiple, the seller is assigned shares at a lower effective cost basis. This lower cost is calculated by subtracting the premium collected from the strike price of the put option.
Khouw noted that investors could further lower their cost basis by writing upside covered calls after being assigned the shares. He referred to this method of entering a stock and then writing covered calls as "the wheel strategy." This structure allows an investor to either acquire the stock at a self-determined price or collect premium for assuming the risk of a price decline.
The strategy relies on the company’s position in the infrastructure sector, which Khouw described as providing the heavy lifting for growth in that area. He argued that this structural advantage justifies the trading approach. Khouw disclosed that Tidal owns or holds all securities mentioned in his analysis. He also stated that the opinions expressed are his own and do not reflect the views of CNBC or its parent company.
The analysis serves as informational content and does not constitute financial, investment, tax, or legal advice. Khouw emphasized that the general nature of the content may not reflect any individual’s unique personal circumstances. He advised readers to consider seeking advice from their own financial or investment advisor before making decisions.
More Business · Bad Business · Report a business · Got a Story?